Friday, September 11, 2026 at 11:10 AM
Options Theta Short term strategy
Theta - First order greek
Theta is the sensitivity of the price of the option when the time passes.
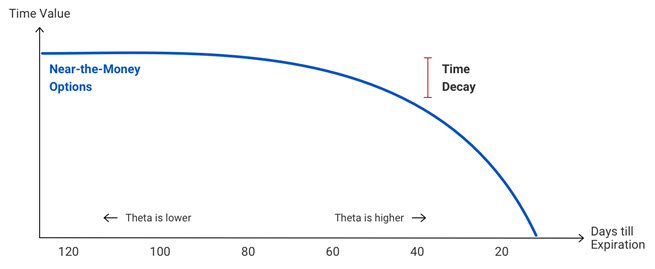
We observe in the theta decay graph that the shorter to maturity, the larger the impact of theta in the price of the option. It simply means that theta accounts for a bigger move in the price of the option close to maturity. Therefore, a volatility strategy could be interested to implement during that period.
Volatility strategy to capture as much theta and Vega as possible
As mentioned in the last 40 days, theta is decaying faster and faster. Options are less and less expensive as time passes. Some volatility traders could interesting to look into options were the Implied Volatility is high, too high than their realized volatility expectation. For instance, for earnings events pricing high IV but the trader believes no major news or results are as expected, then the underlying was already priced in and no major move is going to happen. During these events it could interesting to collect not only the Vega but also the Theta, through OTM sells of call spreads for example. NB: Vega is the sensitivity of the price of the option when the volatility changes. A call spread is buying a call at a strike lower than you sell a put. So, shorting a call spread is the inverse position.
Conclusion
Selling options is risky, because the payoff is largely assymetric and margin is reauired. Only one Black Swan event happen, and 10 previously premium received can be erased, regarding how you construct the short call spread. Therefore this could be an interesting strategy to implement when the thesis about a stock with abnormal IV and short dates Matu is happening.